Hull & Machinery and P&I Insurance: How They Work Together to Protect Your Boat
Understand how Hull & Machinery and P&I insurance work together, with practical examples of damage, liability, collision claims and wreck removal.
- Hull & Machinery protects the boat itself; P&I protects you against liabilities towards others.
- Check whether your hull cover includes partial damage or only total loss.
- Machinery cover is not a maintenance contract: wear and tear is treated differently from accidental damage.
- Collision liability and wreck removal can sit under different policies, each with its own limits.
- Declare how the boat is really used, especially before starting any charter activity.
A grounding, a collision or an injury on board can create several different types of loss. There may be damage to the boat itself, a claim from another vessel’s owner, medical expenses or an obligation to remove a wreck.
These consequences do not necessarily fall under the same insurance cover.
Hull & Machinery insurance and Protection & Indemnity insurance, commonly called P&I, address different aspects of maritime risk. Understanding how they interact helps owners assess whether their insurance arrangements reflect the way their boat is actually operated.
1. Hull & Machinery: protecting the boat itself
Hull & Machinery insurance primarily addresses physical loss of or damage to the insured boat, including machinery and equipment within the policy’s definition.
Depending on the terms, insured events may include grounding, collision, fire and other accidental damage. However, the heading on a quotation does not tell you everything about the protection offered.
An important distinction is whether the policy covers partial damage or is restricted to total loss.
With suitable partial damage cover, repairs following an insured grounding may be recoverable even when the boat remains repairable. Under a policy limited to total loss, the same repair bill may fall outside cover.
Example: damage following a grounding
A boat suffers damage to its propellers, shafts and hull after grounding. The accepted repair cost is USD 85,000.
Assume the incident is fully covered and the policy applies a fixed deductible of USD 10,000. With no other deductions or limitations, the illustrative insurance payment would be USD 75,000.
A total loss only policy would not normally respond to that repair bill simply because the amount is substantial. The event would need to meet the policy’s definition of an insured total loss.
The practical question is therefore: “Does my insurance cover repairable damage, and on what basis?”
2. Machinery cover is not a maintenance contract
The inclusion of machinery does not mean that every engine failure is insured.
Policies may distinguish between an external accident, a defective component, gradual deterioration and damage resulting from that component’s failure.
Some wordings exclude the failed or worn part itself but cover certain resulting damage. Other wordings are more restrictive.
Example: a worn component causes further damage
A worn cooling system component fails and the engine overheats.
There are two separate questions: whether the failed component is covered, and whether the resulting engine damage is covered.
The answer depends on the cause, the applicable machinery provisions and any relevant exclusions. An owner should not assume either that the entire claim is covered or that every consequence of wear is automatically excluded.
Maintenance records, service reports and the surveyor’s findings can become important when establishing what happened.
Share your boat’s details and a BPY specialist will review the structure of your cover with you. Independent advice, no obligation.
3. P&I: addressing liabilities arising from boat operations
P&I focuses on specified liabilities, costs and expenses connected with owning or operating the boat.
Depending on the policy, it can address liability involving guests, crew, other property, pollution and wreck removal. Legal costs associated with a covered claim may also be included, subject to the insurer’s requirements.
The distinction between an injury and a liability claim matters. A guest being injured does not, by itself, establish that the owner is legally responsible.
Example: a guest is injured on board
A guest falls while using the boarding arrangements and alleges that they were unsafe.
The claim might involve medical expenses, lost earnings and compensation. Investigation would consider the circumstances, the owner’s responsibilities and whether liability exists.
P&I may respond to a covered liability and associated defence costs. It should not be treated as a substitute for every guest’s travel or personal medical insurance.
4. Collision claims can involve both policies
Following a collision, damage to your own boat is generally considered under Hull & Machinery.
Liability for damage to the other vessel requires closer examination. Some hull wordings include collision liability, while others leave more of that exposure to P&I.
Certain traditional arrangements allocate three quarters of specified collision liability to hull insurance, with the remaining quarter addressed by P&I. Other arrangements provide a different allocation.
This is a policy structure to verify, not a universal rule.
Example: two boats are damaged
Your boat sustains USD 60,000 of damage, and you are held responsible for USD 120,000 of damage to another boat.
Your own repairs and your liability to the other owner are separate parts of the claim. Their allocation depends on the wording of both contracts.
The insurers should confirm how the policies fit together, including applicable deductibles. P&I should not be assumed to reimburse a hull deductible or automatically fill every exclusion in a hull policy.
5. Wreck removal is a separate financial exposure
The loss of the boat and the obligation to remove its wreck are different issues.
A hull settlement addresses the insured loss of the vessel. Wreck removal cover addresses qualifying removal liabilities and costs, subject to its own conditions.
Example: a sinking near a navigation channel
A boat insured for USD 700,000 sinks. The relevant authority requires removal, and specialist contractors estimate the work at USD 250,000.
The boat’s insured value does not automatically provide an additional USD 250,000 for removal.
The policy review should establish where qualifying wreck removal costs are insured, which limits apply and how the hull and P&I provisions interact.
Pollution prevention or cleanup could introduce another category of expense requiring separate assessment.
6. The declared operation must match reality
A privately used boat, a crewed charter vessel and a boat carrying paying passengers can present different insurance requirements.
Owners should describe their actual operation, including cruising areas, crew arrangements, passenger numbers, tenders and water activities.
Example: introducing charter trips
An owner initially insures a boat for private use, then starts accepting paid bookings.
Before the first charter, the owner should obtain confirmation that the proposed activity is accepted under both hull and liability arrangements. Assuming that an existing policy automatically extends to commercial use can create uncertainty precisely when a claim arises.
The same review is useful before adding activities such as diving excursions or changing the cruising programme.
7. Compare the structure, not just the premium
When reviewing quotations, ask for clear answers to the following questions:
- Does the hull cover include partial damage?
- How will the boat’s value be assessed after a total loss?
- Which machinery losses are excluded?
- How is collision liability allocated?
- Are crew, guests and the intended activities properly addressed?
- What limits apply to pollution and wreck removal?
- Which deductibles could apply to one incident?
- How should claims be reported, and which expenses require the insurer’s agreement?
These details make a quotation meaningful. A premium alone cannot show how much financial risk remains with the owner.
Frequently asked questions
Does Hull & Machinery insurance cover an engine breakdown?
Not automatically. Policies usually treat accidental damage differently from wear and tear or a defective part. Some wordings exclude the worn part itself but cover certain resulting damage, so check the machinery provisions of your policy.
Who pays for damage to the other boat after a collision?
It depends on the wording of both contracts. Some hull policies include part or all of the collision liability, while others leave more of it to P&I. Your insurers should confirm how the two policies fit together.
Is wreck removal included in my boat’s insured value?
No, not automatically. Wreck removal is a separate exposure with its own conditions and limits. Check where it is insured and which limit applies.
Share your boat’s specifications, intended use and cruising plans with our team to discuss Hull & Machinery and P&I arrangements suited to your needs.
All examples are fictional and simplified. Actual cover and claim payments depend on the agreed policy wording, insured circumstances, limits, deductibles and exclusions.
Explore our solutions
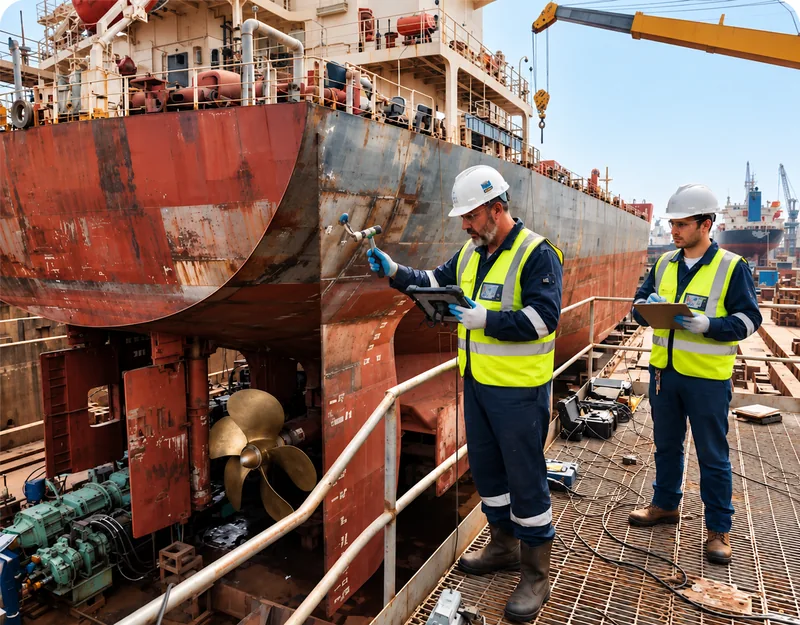
Protection for your vessel, machinery and equipment against insured physical loss or damage.
Learn more →
Liability protection for third party, passenger, crew and other maritime liabilities.
Learn more →
Medical, accident and evacuation benefits designed to protect the people working on board.
Learn more →